Why parsonages are loved and loathed
Parsonage walls don’t talk. But ministers and their families who…

|
Getting your Trinity Audio player ready...
|
Churches may help ministers with housing costs in a variety of ways. Among the most common are parsonages, housing allowances and loans or gifts for a down payment.
Parsonages are homes owned by the church for use by the minister, most commonly the lead minister but sometimes youth ministers or other ministry staff.
The parsonage may be a freestanding house on church property, a house elsewhere in the community or an apartment attached to the church building.

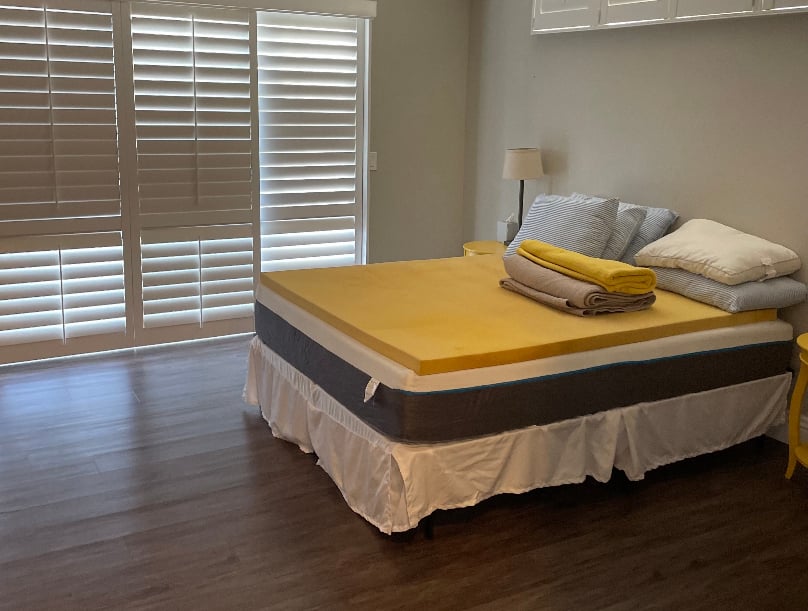
An unmade bed in the Canyon View Church of Christ parsonage in between occupants.
Kris Southward, an elder of the University Church of Christ in Abilene, Texas, is a certified public accountant. His firm has filed tax returns for ministers and missionaries for 37 years.
Ministers pay income tax on salary just like everyone else, but housing is treated differently. Southward explained to The Christian Chronicle how the parsonage works from a tax standpoint.
“A minister lives there, and that’s income tax-free, but they do have to pay Social Security taxes (self-employment tax) on the rental value of the house,” he said. “So if the house could rent for $2,000 a month, then the minister doesn’t pay income taxes on that portion of his salary.”
Southward and his partner work with 40 to 50 ministers and missionaries a year, fewer than in the past, he says, because “there are fewer American missionaries these days.” He recently sold his firm and will retire at the end of 2024.
Opting out of Social Security is an option for ministers that was more popular in the 1970s and 1980s, exercised as a separation of church and state matter, but with the rationale that the minister could invest the same amount himself and earn more in the long run. Opting out required ministers to make a statement of conscientious objection to accepting public insurance because of religious beliefs.
Related: Why parsonages are loved and loathed
That trend has changed, which Southward believes is a good thing, because typically that investment never happened.
“I see it very rarely,” he said. “Once you opt out, you can’t get Medicare, and you can’t get back into Social Security — as long as you’re a minister, you are out.”
In the 1990s, the IRS offered a one-time chance to get back in the Social Security system.
“Once you opt out, you can’t get Medicare, and you can’t get back into Social Security — as long as you’re a minister, you are out.”
Southward said the rental value of the parsonage should be determined annually with an appraisal by a real estate agent or other professional, but often the process is less formal.
The same tax principles apply when churches instead offer a housing supplement, often called a housing allowance. Rather than own a home, the church designates a portion of the minister’s salary for housing costs, and that portion of salary is not subject to income tax so long a it’s fully used for housing expenses during that year, but again is subject to self-employment taxes unless the minister has opted out of Social Security.
So, for example, if a minister receives a salary of $80,000 a year and anticipates housing costs of $2,000 a month, the church should issue a letter annually stating that $24,000 of the minister’s compensation is a housing allowance. That portion will not be subject to income tax. The IRS limits the value of the housing allowance to fair rental value of contents of the home and utilities, Southward said.
The housing allowance relieves the church from the obligations of owning and maintaining a property, but more significantly, it permits the minister to build equity in a home, which often is his or her largest or only investment for retirement other than Social Security.

Karen and Kris Southward in their 2023 Christmas photo.
Some churches have turned to other arrangements to help ministers. The young preacher just starting out, or one who has always been in the parsonage system, may have no means of making a down payment to get into a home.
Southward has known of churches that lend money at no interest or a very low interest that may be forgiven over a period of years. The tax implications of such arrangements would vary according to the terms of the loan, so it’s important to consult an attorney and accountant and put the details in writing. This also protects the minister if there’s a turnover in the eldership after a few years. The new elders can’t say, “We didn’t make that deal.”
Parsonage walls don’t talk. But ministers and their families who…
TUCKERS CROSSROADS, Tenn. — The Bethlehem Church of Christ has a…

OKLAHOMA CITY — The Mayfair Church of Christ — at…

LOS ANGELES — At age 13 in 1983, I moved…

LA MESA, Calif. — It may take a miracle. That’s…

One of the most difficult questions to answer when pursuing…
Your donation helps us not only keep our quality of journalism high, but helps us continue to reach more people in the Churches of Christ community.